What this note is about
The binomial tree is the computational engine for every contract that breaks the Black–Scholes closed form: American early exercise and path-dependent barriers both reduce to the same backward-induction pass with a one-line modification. This note sets up the model — the assumptions (Bi1)–(Bi3), why the tree recombines, and how the three parameters , , are pinned down by forcing the discrete model to imitate risk-neutral GBM over each step. Two equations match mean and variance; the third is a free design choice whose classic value (Cox–Ross–Rubinstein) gives a symmetric tree ideal for barriers. The full algebra lives in the CRR-parameter derivation.
Learning objectives. By the end of this note you should be able to:
- state the binomial assumptions (Bi1)–(Bi3) and explain why the tree recombines;
- derive the mean-matching equation and the risk-neutral probability ;
- derive the variance-matching equation and explain the role of the third equation ;
- quote the exact CRR solution and its approximation , and interpret it;
- compute numerically for given .
One-step binomial model and replication
Refresher from market model and risk-neutral valuation: over one period the stock moves or with . Replicating the option with shares and cash forces
Here are the option's known values in the two successor states, and is the risk-neutral probability: it is a genuine probability () exactly when , which is forced by no-arbitrage . Under , . Real-world probabilities never enter.
Financial interpretation. The hedge ratio is the discrete ancestor of . Pricing by replication and pricing by discounted risk-neutral expectation give the same number because the price is the cost of the hedge.
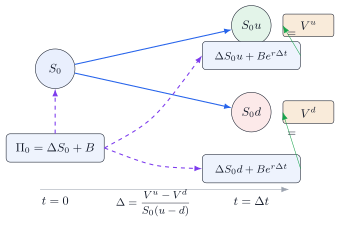
Remark 1.1 (completeness). With two unknowns in the hedge portfolio (shares and cash) and two future states, replication has a unique solution for any payoff — the one-step market is complete. This is the entire reason the binomial model prices uniquely; with three or more states per step a single stock and bond could no longer replicate everything .
The multi-step tree
Divide into steps, , .
Assumptions 1.2 (Bi1)–(Bi3).
- (Bi1) over each , or , with and the same at every node;
- (Bi2) , the same at every node;
- (Bi3) expectation and variance of the discrete model match those of continuous risk-neutral GBM.
(Bi1)+(Bi2) make the tree homogeneous; (Bi3) is the calibration requirement that makes the tree a discretisation of our model rather than an arbitrary lattice.
Proposition 1.3 (node values and recombination). The node reached by up-moves out of steps has value
Because , the order of moves is irrelevant — the tree recombines: after steps there are only distinct values, not , and the total node count grows quadratically in .
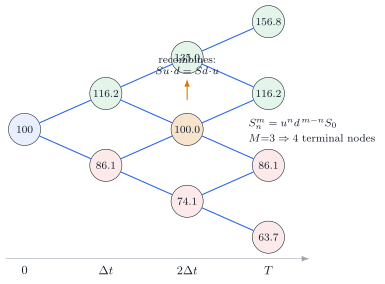
Why recombination matters computationally: paths vs nodes for . Recombination is the difference between exponential and polynomial cost. (It breaks when discrete dividends shift nodes off the lattice — see backward induction and the binomial algorithm.)
At expiry there are terminal prices , spanning .
Deriving , , — matching the continuous model
Three unknowns need three equations. The first two implement (Bi3); the third is ours to choose.
Equation 1 — match the mean. Discrete one-step mean: . Continuous risk-neutral GBM: . Equating and dividing by :
Note this is the same as in section 1: matching the risk-neutral mean and pricing by replication produce one number.
Equation 2 — match the variance. Continuous risk-neutral GBM satisfies , so per unit :
This is where enters the tree — the spread between and must reproduce the model's variance.
Equation 3 — a free design choice. Impose for a chosen constant . The classic choice is (Cox–Ross–Rubinstein): symmetric up/down moves, so the tree's central line grows vertically.
Theorem 1.4 (CRR solution). With and :
Up to higher-order terms in this gives the familiar CRR parameters
Full step-by-step algebra: the CRR-parameter derivation.
Remark 1.5 (reading the solution). The tree's vertical extension per step is in log-space — one standard deviation of the continuous model's log-return. The is the diffusive scaling from stochastic processes, Brownian motion and Itô's lemma: noise grows like the square root of time, and so must the lattice.
Example 1.6 (numerical calibration). Take , , , , so . CRR approximation:
Sanity checks: ✓; ✓.
Summary table — the three ingredients:
| Requirement | Equation | Consequence |
|---|---|---|
| no-arbitrage / martingale mean | , valid iff | |
| volatility matching | spread | |
| normalisation | free choice | : symmetric tree (good for barriers); : tilted tree (good convergence) |
Exercises
Exercise 1.1. Verify that with the exact CRR solution (Theorem 1.4), Equations 1 and 2 hold identically.
Solution. Since , we have and . Equation 1 holds by construction of . For Equation 2, using :
**Exercise 1.2 . Expand and in powers of to show .
Solution. With , , so and .
Exercise 1.3. For , , , , write out all five terminal stock prices and verify the tree spans .
Solution. Terminal nodes: giving . Span: , matching .
Exercise 1.4. A colleague proposes , , , . Show that and construct the explicit arbitrage.
Solution. , so . Short the stock, deposit proceeds: profit in the up state and in the down state — riskless profit above the bank rate.
**Exercise 1.5 . Explain in one paragraph why Shreve's multi-period model uses the same at every node rather than calibrating locally to a term structure of volatility.
Solution. Homogeneous make the tree recombining and keep node count . Local calibration would break recombination (each node carries its own geometry), exploding memory to unless a state-space collapse is engineered. For equity options with flat the homogeneous tree is the standard; term-structure effects require implied-vol interpolation or a trinomial tree with time-dependent parameters .
This is a sample from the full curriculum. Members get every lesson, exercise solution and project.
See membership options