Projects / Phase 4.3 · JD to Projects
Natural-Gas Storage Valuation, Hedging and LNG Cargo Optionality
What is a storage contract worth, how to run and hedge it, and should the desk buy it?
Headline result
Valuation, hedging and a bid-or-pass rule for a 1 Bcf salt-cavern lease, scored on 57 monthly offers from 2019 to 2023. The average lease was valued at $358k and realised $330k; one-day execution lag and unhedged days gave back $877k of $1.03M re-optimisation gains. The bid rule made $10.7M against −$0.6M for always bidding.
Figures
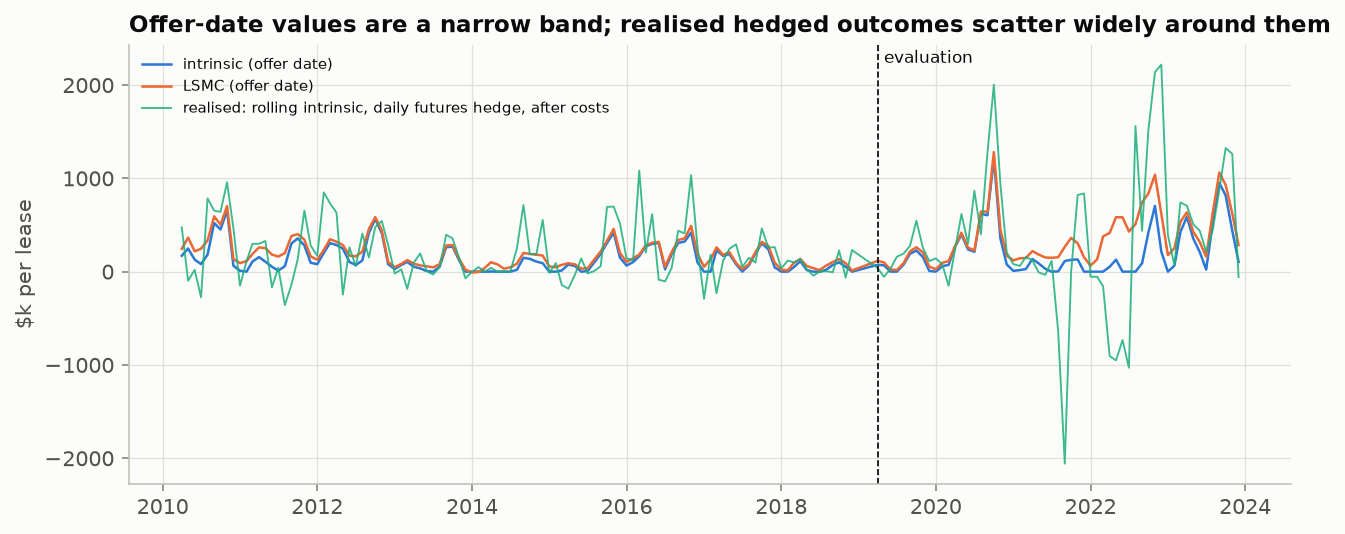
Model values form a narrow band while realised outcomes scatter widely, from a $2.1M loss in September 2021 to over $2M. 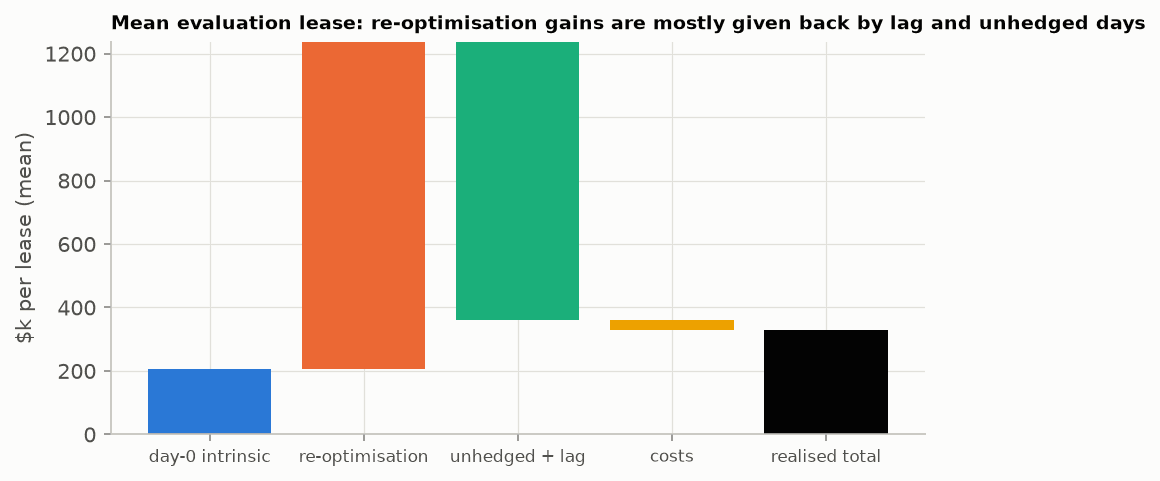
Re-optimisation adds $1.03M on paper, but execution lag and unhedged days give back $877k, leaving $330k realised. 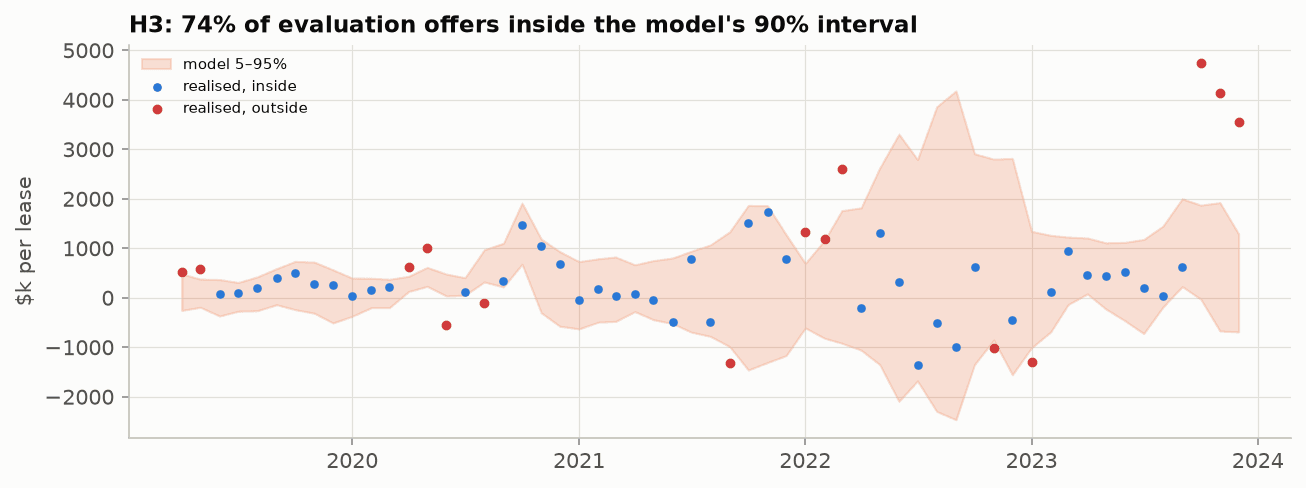
Only 74% of outcomes fell inside the model’s 90% interval, against 85% required; the largest misses are late-2023 offers above $3.5M. 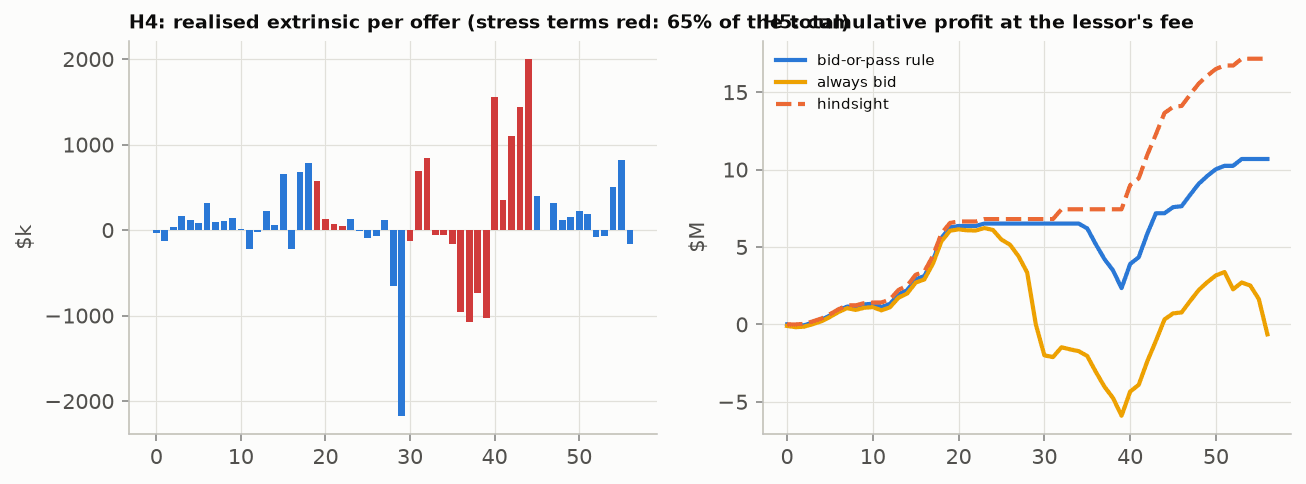
Offers struck before Winter Storm Uri (2021) and in 2022 carried 65% of realised extrinsic value; the bid-or-pass rule made $10.7M against −$0.6M for always bidding.
Data used
- NYMEX natural-gas futures settlements (contracts 1–4) as republished by EIA, 1993 to Apr 2024
- Henry Hub daily spot from EIA, 1997 to Oct 2026
- EIA weekly working-gas storage reports, 2010 to Oct 2026
Built from Gas Valuation and Structuring Quant job descriptions
The role asks for
- Storage and structured deal valuation
- Monte Carlo and optimisation methods
- Commodity derivatives pricing and hedging
- Risk measurement and P&L explain
- Python
- Working closely with traders
This project uses
- Two-factor forward-curve model
- Least-squares Monte Carlo storage valuation
- Rolling intrinsic with futures hedging
- Dual upper bounds
- P&L explain and VaR backtesting
- Bid-or-pass deal rule
Members open the full write-up, notebook, tested code and data in the project reader.